members only
Nebius Q3 2026 recap: A strong but messy quarter
Nebius beat Q3 revenue estimates but shares fell sharply. Here’s the full recap and what it means for the long-term thesis.
Introduction
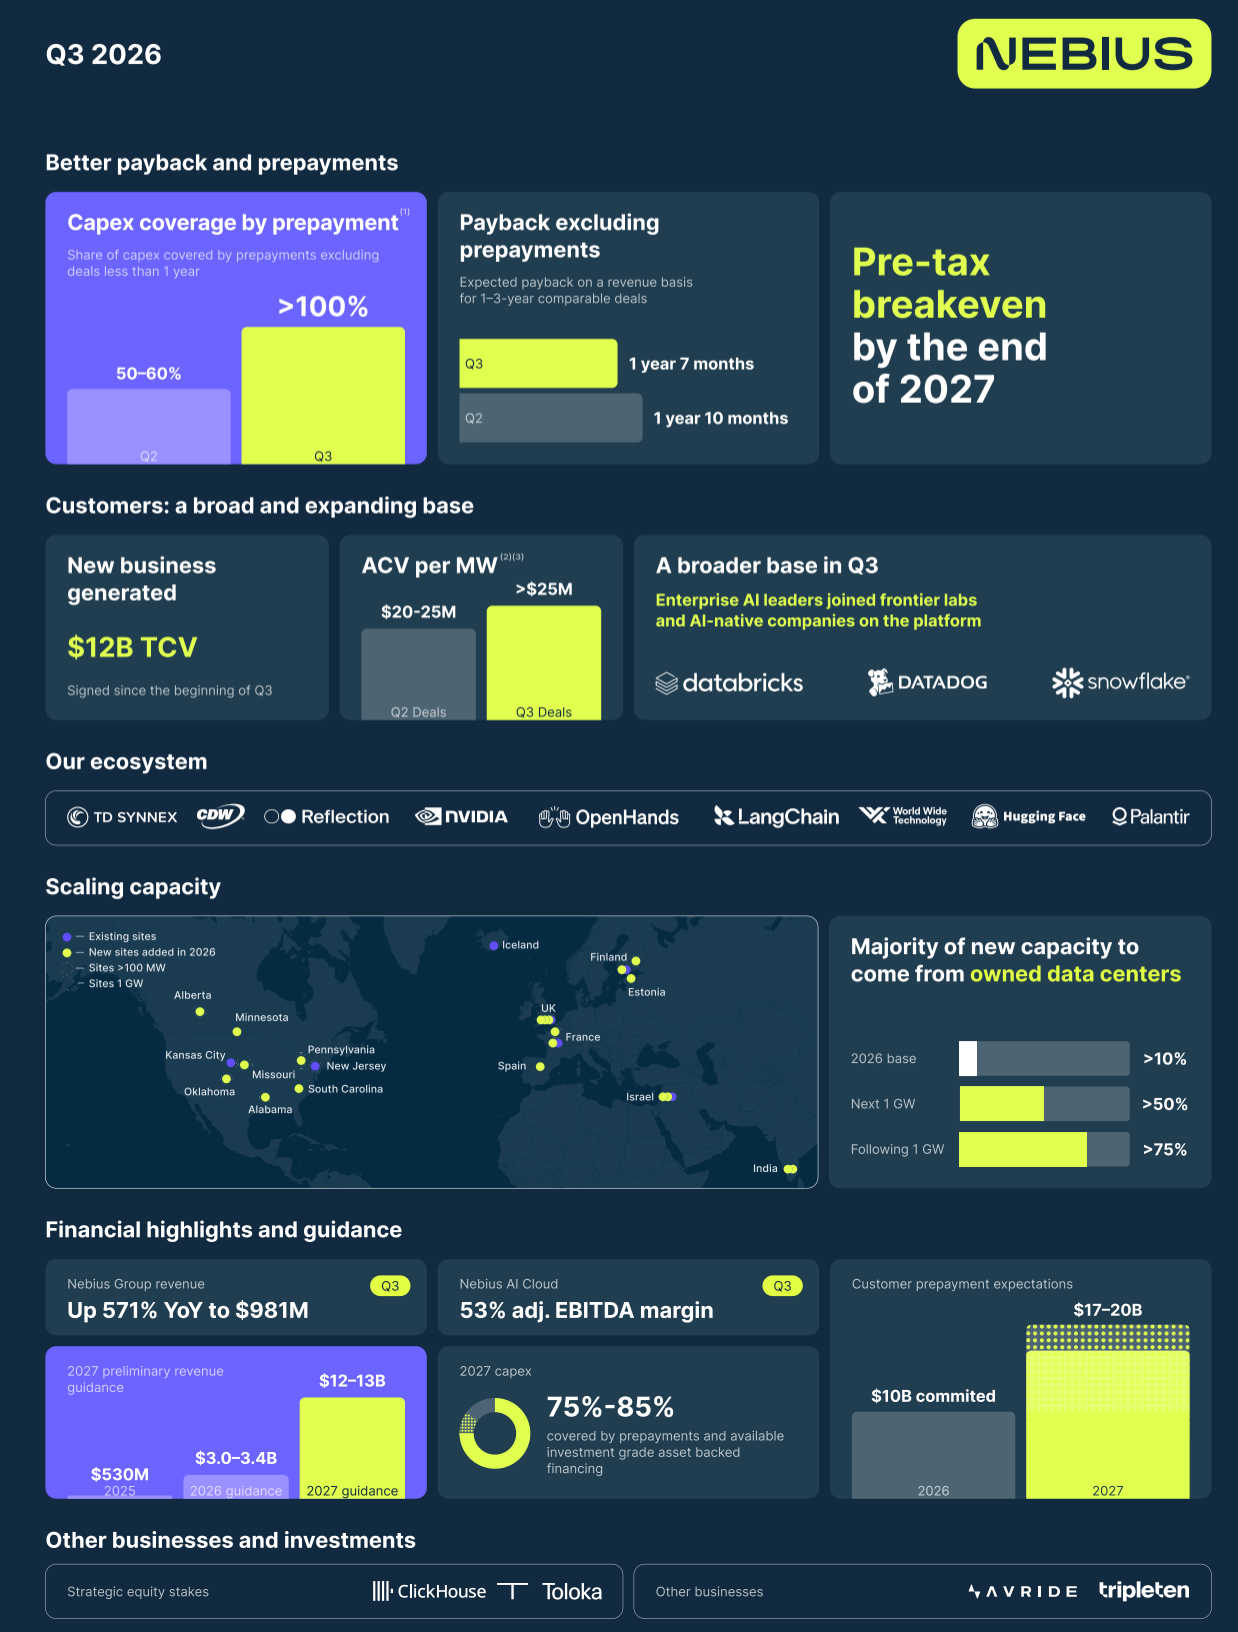
Nebius grew revenue 68% from Q2, turned a GAAP operating profit, and said it expects $12B to $13B in revenue next year (which I think is VERY conservative). The stock fell nearly 18% at the market open today.
So what caused the drop and what are the most important takeaways from this quarter?
I think three things explain the reaction. Some capacity is coming online later than planned. A $325M one-off made the revenue beat look bigger. And Nebius is going to spend even more to get the next wave of capacity built.
I'll break each of these down into more details in this recap. First, let's have a look at the numbers.
The quarter in numbers
- Group revenue of $980.8M, up 571% year over year and 68% sequentially, versus $916.8M estimated
- Nebius AI Cloud revenue of $973.8M and adjusted EBITDA margin of 53.2%
- Group adjusted EBITDA of $465.8M, a 47% margin, and GAAP operating income of $50.4M
- GAAP net loss from continuing operations of $37.5M and diluted loss of $0.13 per share
- Annualized run-rate revenue of $6.4B at the end of September, up from $3.0B in June. Remaining performance obligations reached $38.7B, up 3% sequentially
- $273M of operating cash outflow from continuing operations, $7.3B spent on property, equipment and intangible assets, and $7.4B of cash and cash equivalents at quarter-end
Why the stock sold off
1. Some of the growth moved into 2027
Nebius now expects full-year revenue at the low end of its $3.0B to $3.4B range, against consensus around $3.35B. That implies roughly $1.04B in Q4 after $1.96B through September. Management also pushed out the timing for getting past $7B of annualized run-rate revenue to February 2027. In August, $7B was the low end of its $7B to $9B December target.
Some third-party data center capacity will come online in the first half of 2027. Nebius says the customer contracts remain in place. I think that's the most important part here. We're talking about a timing issue, not a demand issue.
Customers can reserve the GPUs months in advance, but Nebius needs the site powered and the GPUs ready for use before that capacity can start earning cloud revenue. Every month that slips changes the shape of the next few quarters.
2. The $325M one-off flattered the beat
This post is for subscribers only
Subscribe to continue reading
Written by