members only
Cloudflare Q3 2026 recap: Growth accelerates as customers spend more
My take on Workers usage, larger renewals, AI monetization and the margins behind the record quarter.
Cloudflare grew revenue 39% in Q3, added a record number of large customers, and raised its outlook. Net retention climbed to 122%, while non-GAAP operating margin reached a new high.
This was a very strong quarter. What I find particularly interesting is how developer adoption is starting to increasingly show up in customer spending. Companies are using their committed budgets faster and signing larger agreements. Good stuff!
1. What Cloudflare does
For those unfamiliar with what they do: Cloudflare runs a global network that helps customers connect, protect and build internet applications. It can block malicious traffic before it reaches a website, control which employees or agents can access specific systems, and run application code through its Workers developer platform.
Think of an online retailer: it needs its website to load quickly, protection against attacks and unwanted bots, secure access for employees, and somewhere to run new applications. Cloudflare can provide those services through the same network. A customer might arrive for one of them and gradually use more.
The developer platform adds another layer to the business. When a company's developers start building on Workers, Cloudflare has an opportunity to become part of how the business runs, alongside the products protecting it.
2. Key numbers
- Revenue: $782.5M, up 39.2% year over year, versus $734.3M consensus
- Large customers: 5,006, up 25% year over year and 308 sequentially, accounting for 75% of revenue
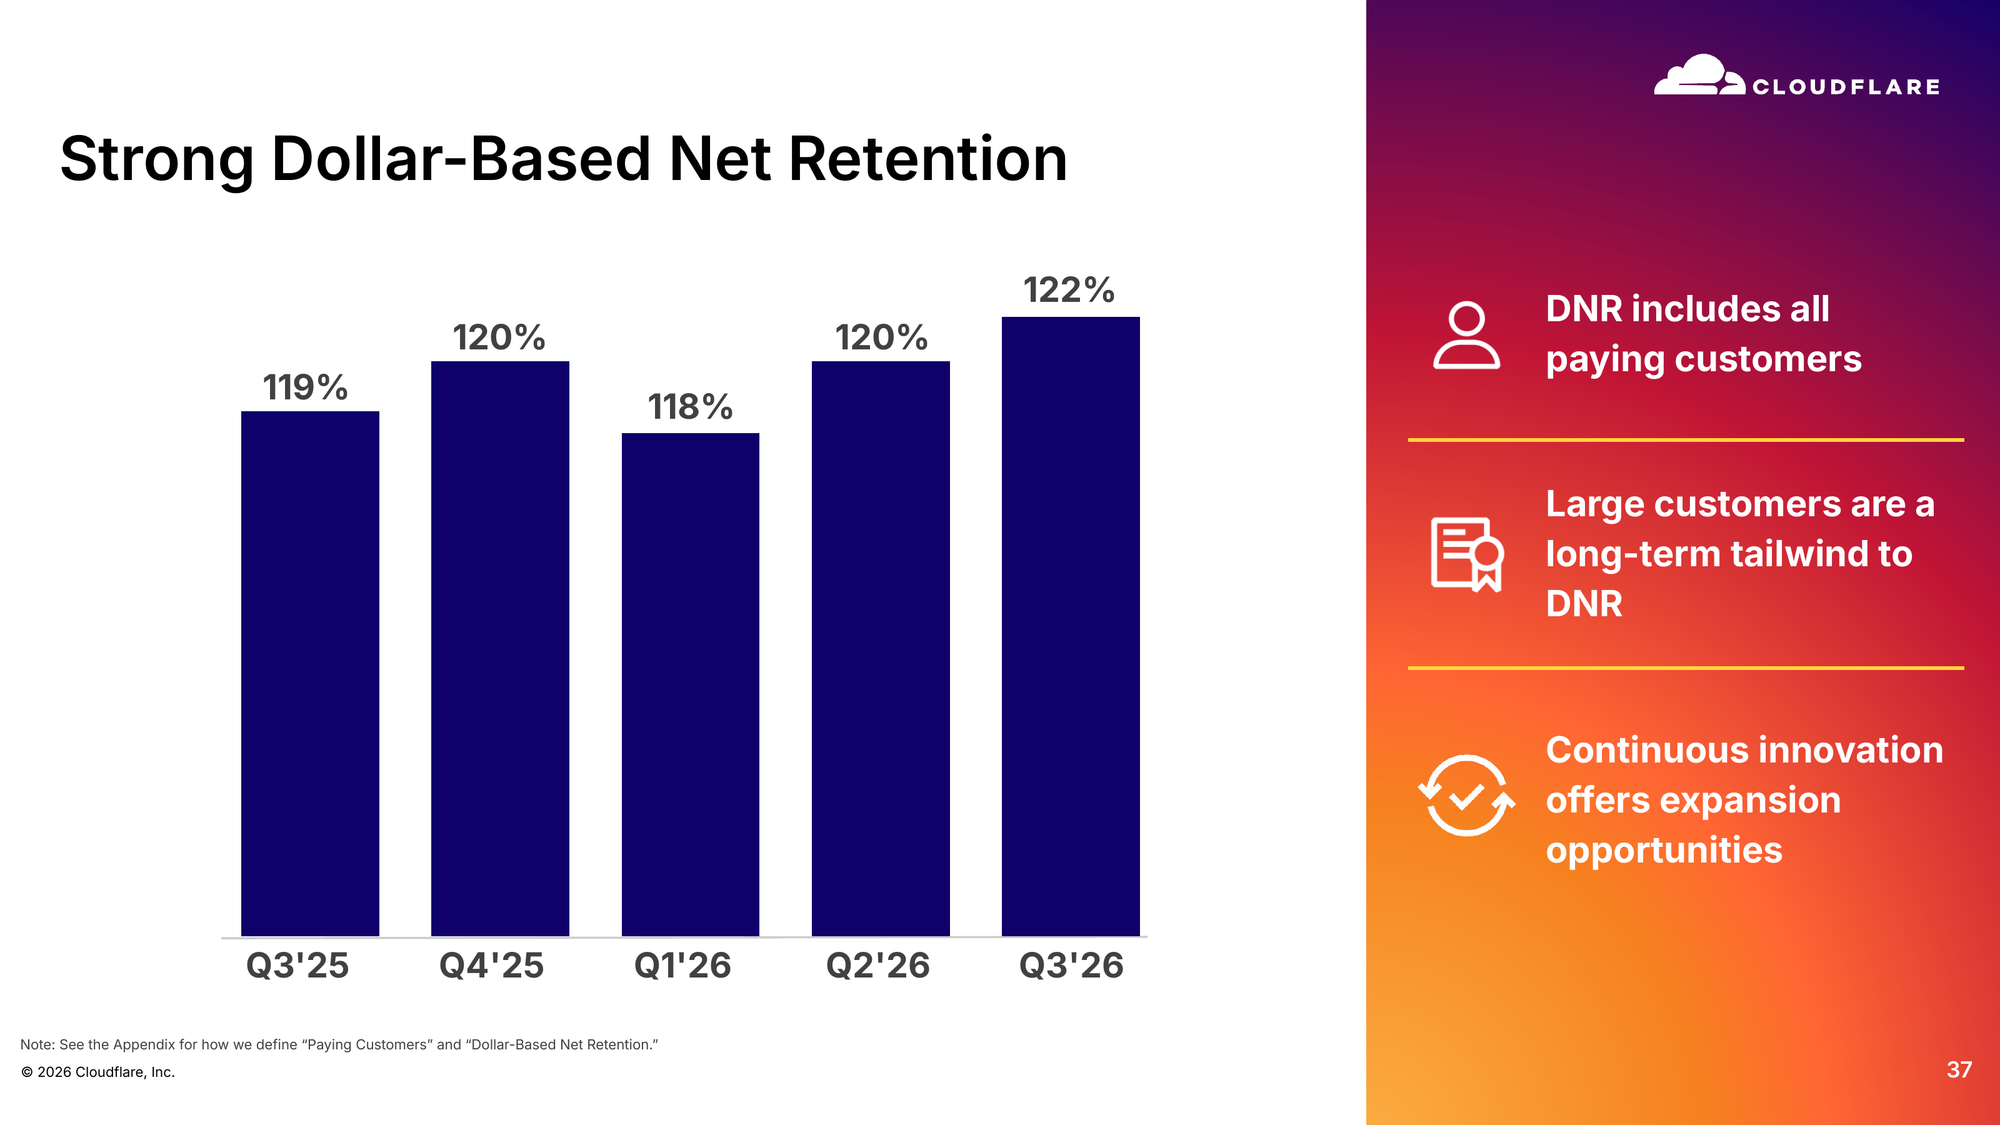
- Dollar based net retention: 122%, versus 120% in Q2 and 119% a year ago
- Remaining performance obligations: $2.877B, up 34% year over year, with current RPO growing 37%
- GAAP gross margin: 71.2%, versus 74.0% a year ago
- Non-GAAP gross margin: 72.4%, versus 75.3% a year ago
- GAAP operating loss: $67.9M, compared with $37.5M a year ago
- Non-GAAP operating income: $137.1M, a 17.5% margin, versus 15.3% a year ago
- Non-GAAP diluted EPS: $0.38, versus approximately $0.346 expected; GAAP EPS was a $0.10 loss
- Free cash flow: $82.1M, up from $75.0M a year ago, at a roughly 10% margin
Revenue came in about 6% above expectations and non-GAAP EPS 10% above adjusted EPS consensus.
Their retention number is especially encouraging. Revenue from the existing customer cohort was 22% higher, after contraction and churn and gradually inching higher.
3. Outlook
This post is for subscribers only
Subscribe to continue reading
Written by