members only
AMD Q3 2026 recap: Data Center almost doubles
Data Center sales nearly doubled, Q4 guidance points to another jump, and cash conversion weakened. My take on AMD’s AI ramp and what it needs to prove.
Introduction
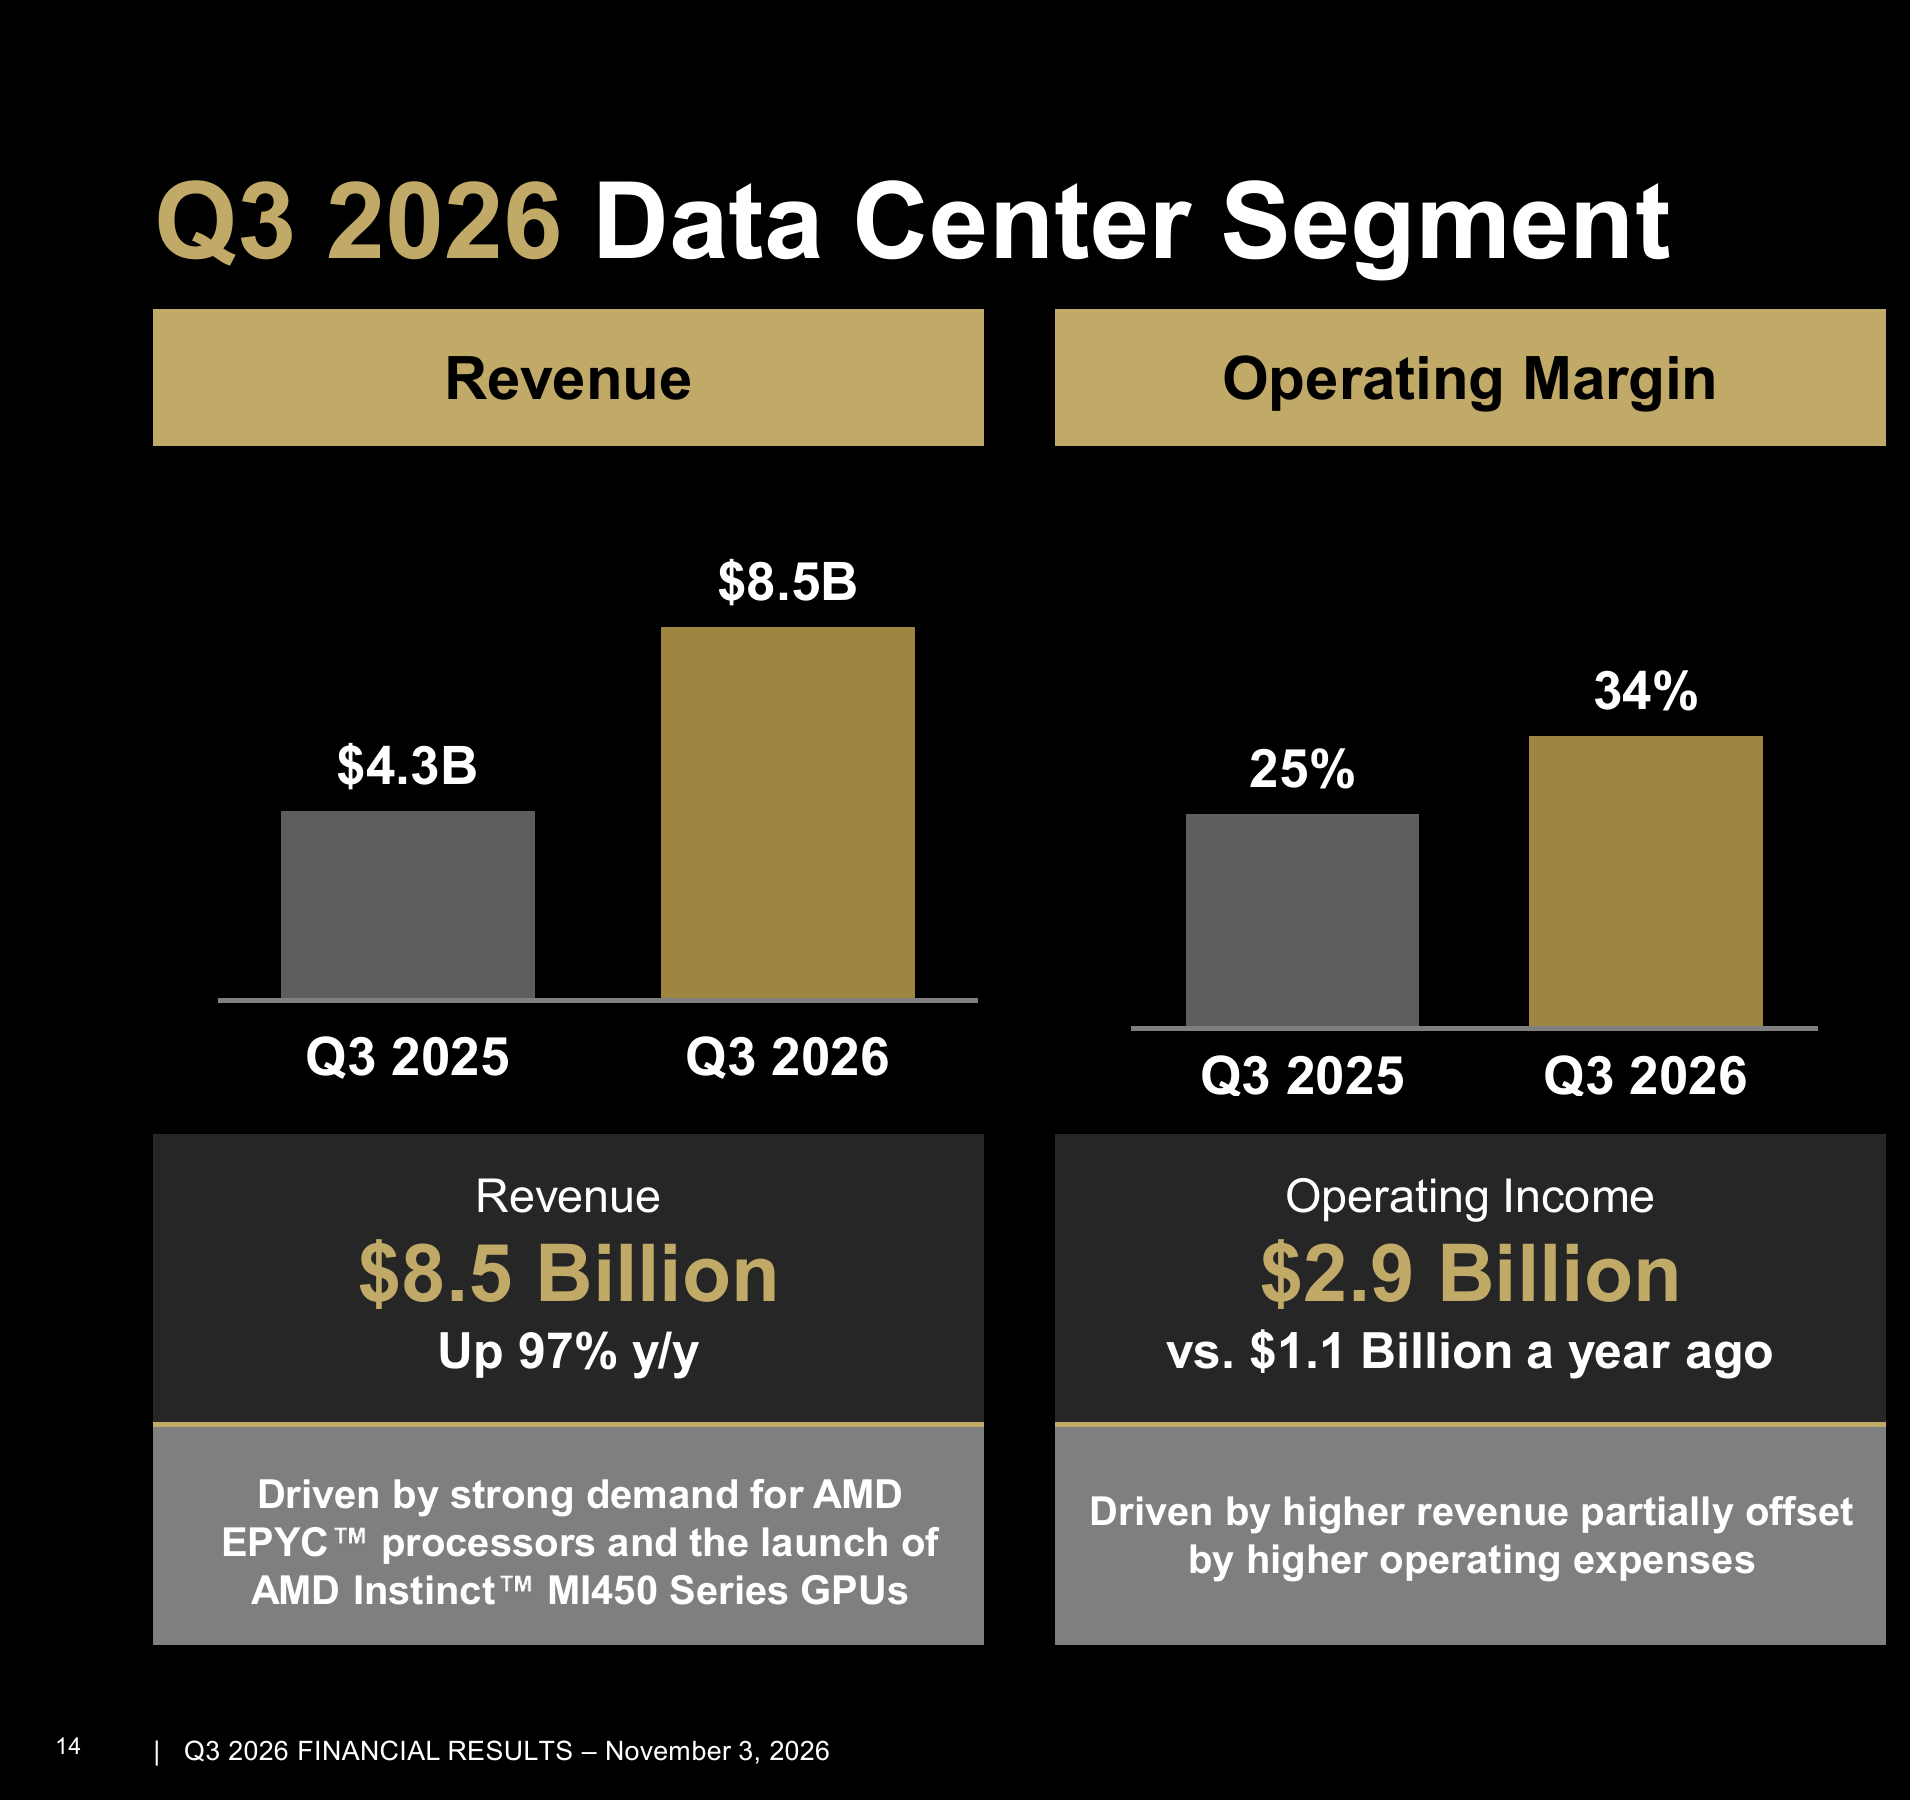
AMD's data center revenue nearly doubled in Q3 and now makes up 64% of the business. The first Helios racks are generating revenue, EPYC server processors are gaining ground, and management expects the whole company to grow more than 80% in 2027.
That's a substantial step up from a company already growing revenue 45%. What I find particularly interesting is that both CPUs and GPUs are contributing. The AI opportunity is becoming much broader than selling accelerators alone.
There are also some things that don't look that bright: a weakening PC market, customer warrants and the cash needed to fund this ramp. Let's walk through the quarter.
1. Key numbers
- Revenue: $13.377B, up 45% year over year and 16% sequentially, versus approximately $13.119B expected
- Non-GAAP diluted EPS: $2.09, up 74%, versus approximately $1.94 expected. GAAP diluted EPS was $1.46
- Data Center revenue: $8.546B, up 97% year over year and 27% sequentially
- Client revenue: $2.949B, up 7% year over year and down 4% sequentially
- Gaming revenue: $773M, down 40% year over year
- Embedded revenue: $1.109B, up 29% year over year and 14% sequentially
- GAAP operating income: $2.832B, a 21% margin, versus 14% a year ago
- Non-GAAP operating income: $3.923B, a 29% margin, versus 24% a year ago
- Gross margin: 54% GAAP and 56% non-GAAP, both roughly unchanged sequentially
- Free cash flow: $554M, down from $1.558B in Q2
- Cash, cash equivalents and short-term investments: $15.776B, against $7.079B of debt
The revenue beat was about 2%, while adjusted EPS came in about 8% above consensus. More interesting to me is the operating leverage. GAAP operating income more than doubled as revenue grew 45%. AMD is spending more on the business, but revenue is growing faster.
Data Center generated almost $2.9B of segment operating income at a 34% margin. That segment includes server CPUs as well as AI accelerators. The nearly doubled revenue figure describes the whole segment, rather than GPU sales alone.
2. Outlook
This post is for subscribers only
Subscribe to continue reading
Written by